BTC US$69.1k. Bitcoin holds firm as Iran war continues
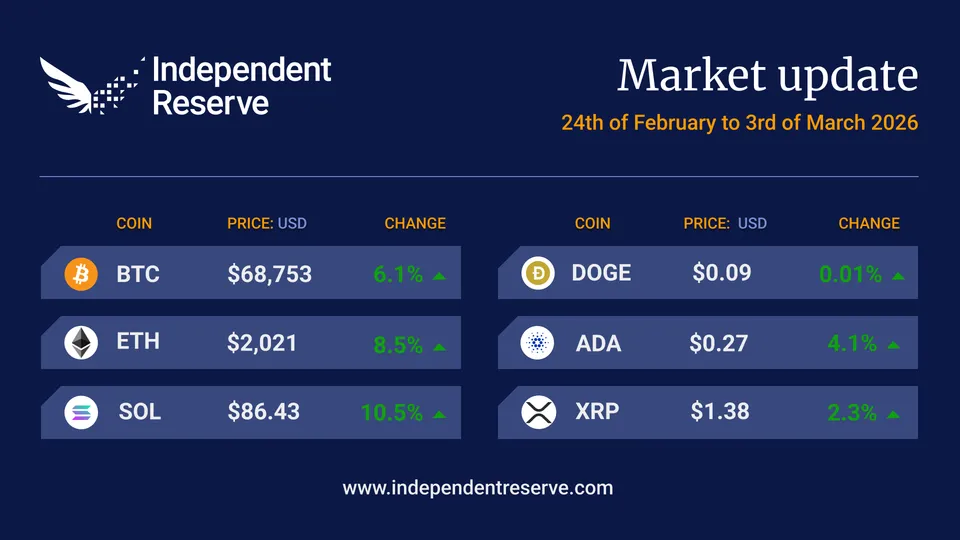
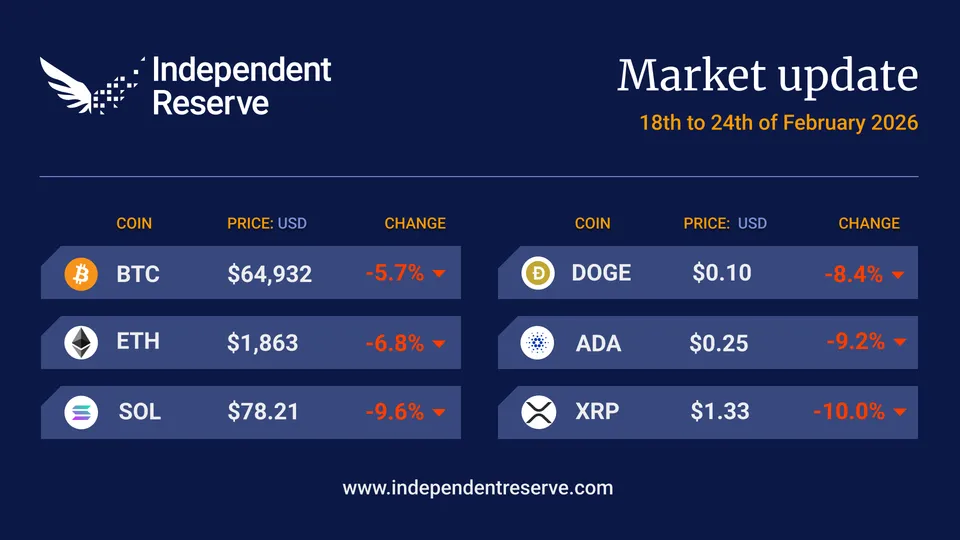
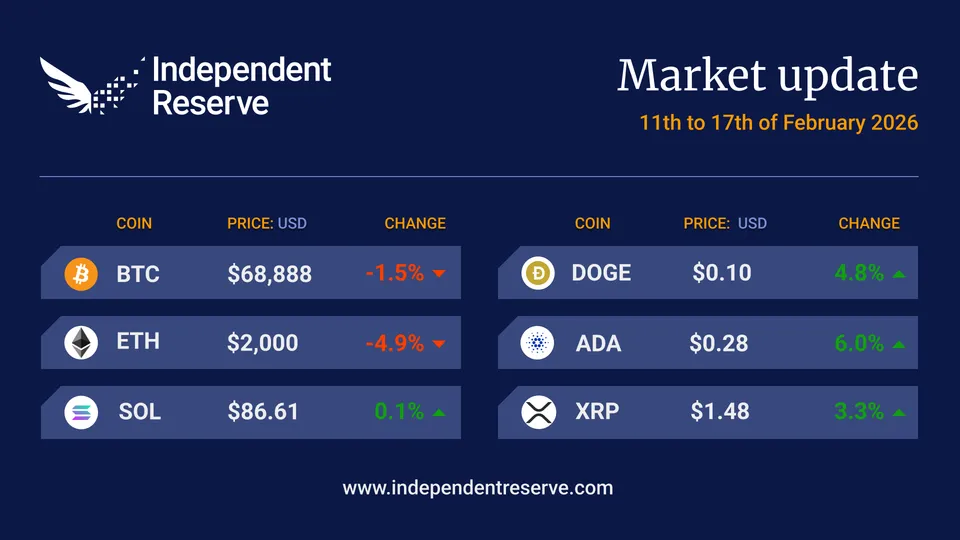
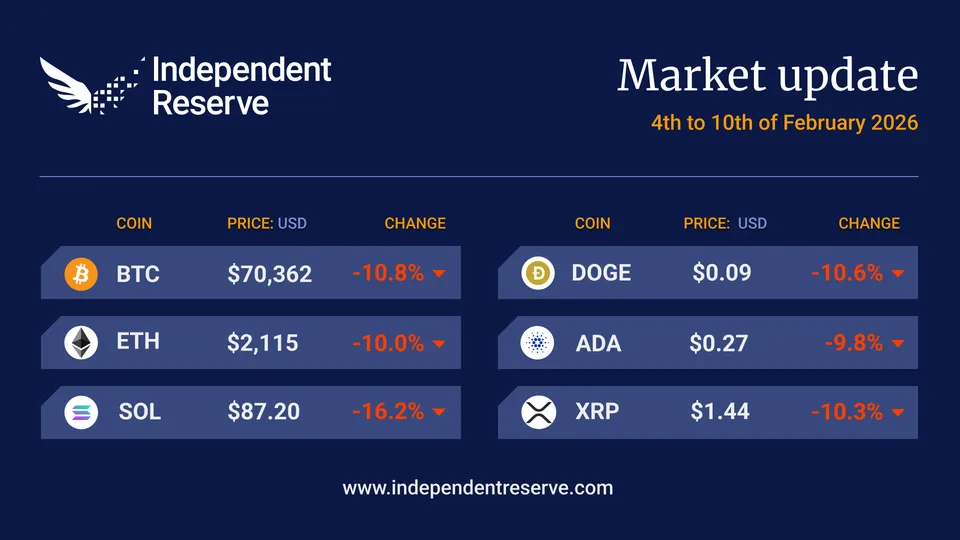
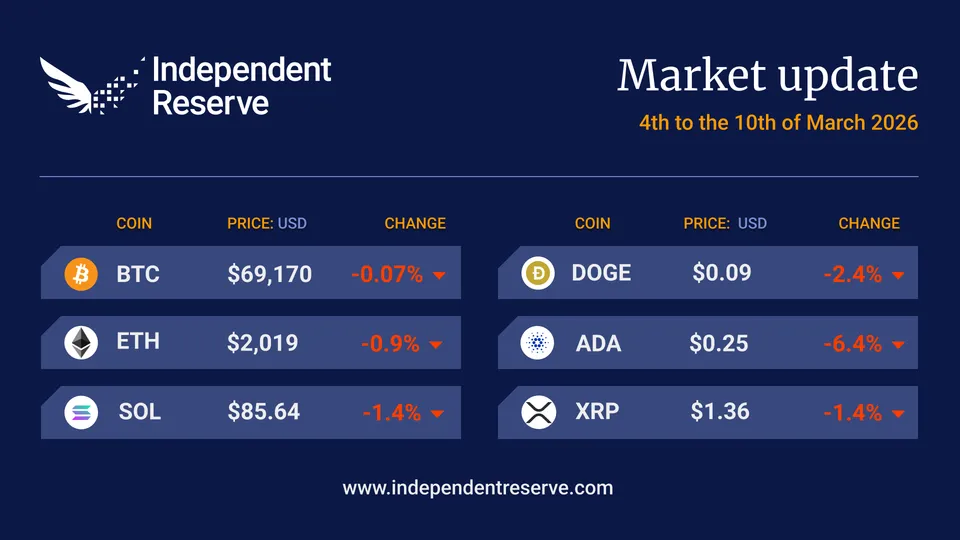
Global markets have had a tumultuous start to the week, with oil prices trading like a pump-and-dump memecoin. Oil prices gained almost 30% yesterday, trading at four-year highs, amid fears that the war in Iran will dramatically squeeze oil supplies through lower production and the closure of the Strait of Hormuz. Stock markets plunged, and NAB analysts warned Australian inflation could surge to 5% as a result. Bitcoin, however, held up well, leading some analysts to suggest the bottom is in. But oil prices have subsequently reversed most of the surge and fallen back below US$90 a barrel. After G7 countries discussed releasing up to 400M barrels from their reserves to shore up supplies, it emerged that oil tankers are crossing the strait with transponders off and after President Trump told CBS, "the war could be over soon." The Kobeissi Letter says this fits the Trump crisis playbook to a tee, although stopping a multi-country war is clearly a lot more difficult than walking back tariffs. We’re not out of the woods yet, with US jobs data suggesting the country lost 92,000 jobs in February, and oil prices remain much higher than a month ago. Bitcoin attempted a breakout above A$104K (US$74K) mid last week, but it didn't hold. After all the drama, Bitcoin finishes the week pretty much where it began - around A$97,820 (US$69.1K). ETH fell by 1% to trade around A$2,856 (US$2,019). XRP lost 1.4%, Solana (-1.4%), Dogecoin (-2.4%) and Cardano (-6.4%). Strategy bought another 17,994 Bitcoin for A$1.8B (US$1.28B), in the largest acquisition since January, and the Crypto Fear and Greed Index is at 13, or Extreme Fear.